
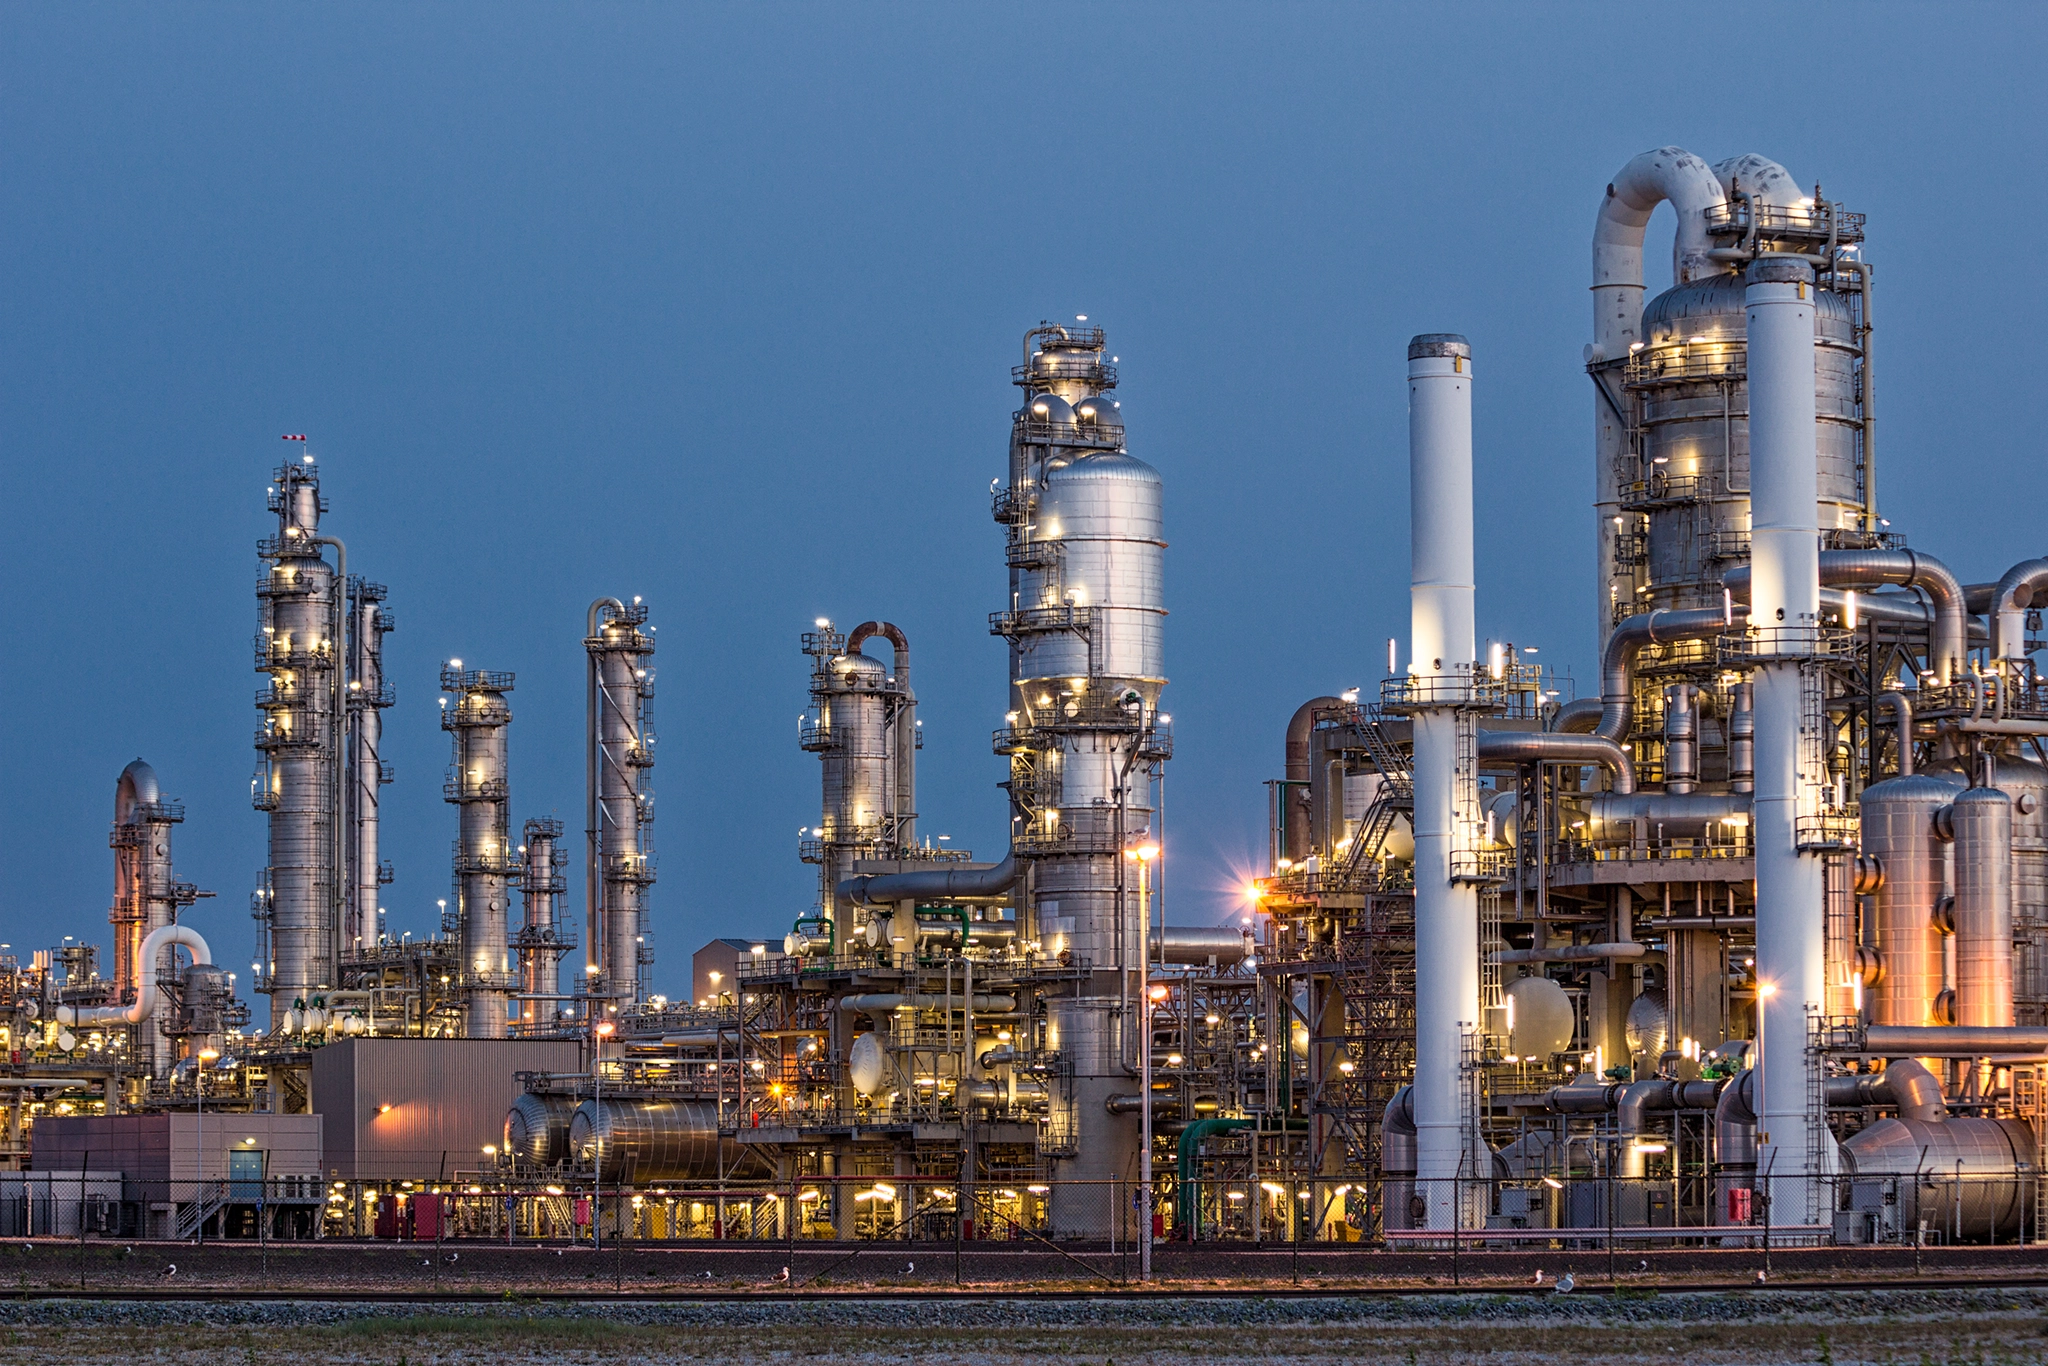
The engine behind this quarter’s performance was not crude oil production, but the transformation of raw materials into finished fuel. Independent refiners dominated the landscape, led by Marathon Petroleum, which posted a 55.1% return, followed closely by Phillips 66 at 51.8% and Valero Energy at 49.4%. These gains were fueled by widening crack spreads—the profit margins between crude oil costs and the value of refined products like diesel and jet fuel—as global capacity disruptions in Russia and the Middle East tightened supply chains.
Integrated majors provided a more stable, diversified counterbalance, averaging a 19.9% gain. Chevron led this group with a 24.3% return, leveraging both upstream production and downstream refining to capture value regardless of market volatility. In contrast, the midstream sector showcased a stark divide: while marine shipping companies like Dorian LPG and Frontline soared on the back of longer global trade routes and increased shipping demand, traditional pipeline operators such as Enbridge and TC Energy saw share prices decline.


Comments (0)
No comments yet. Be the first!