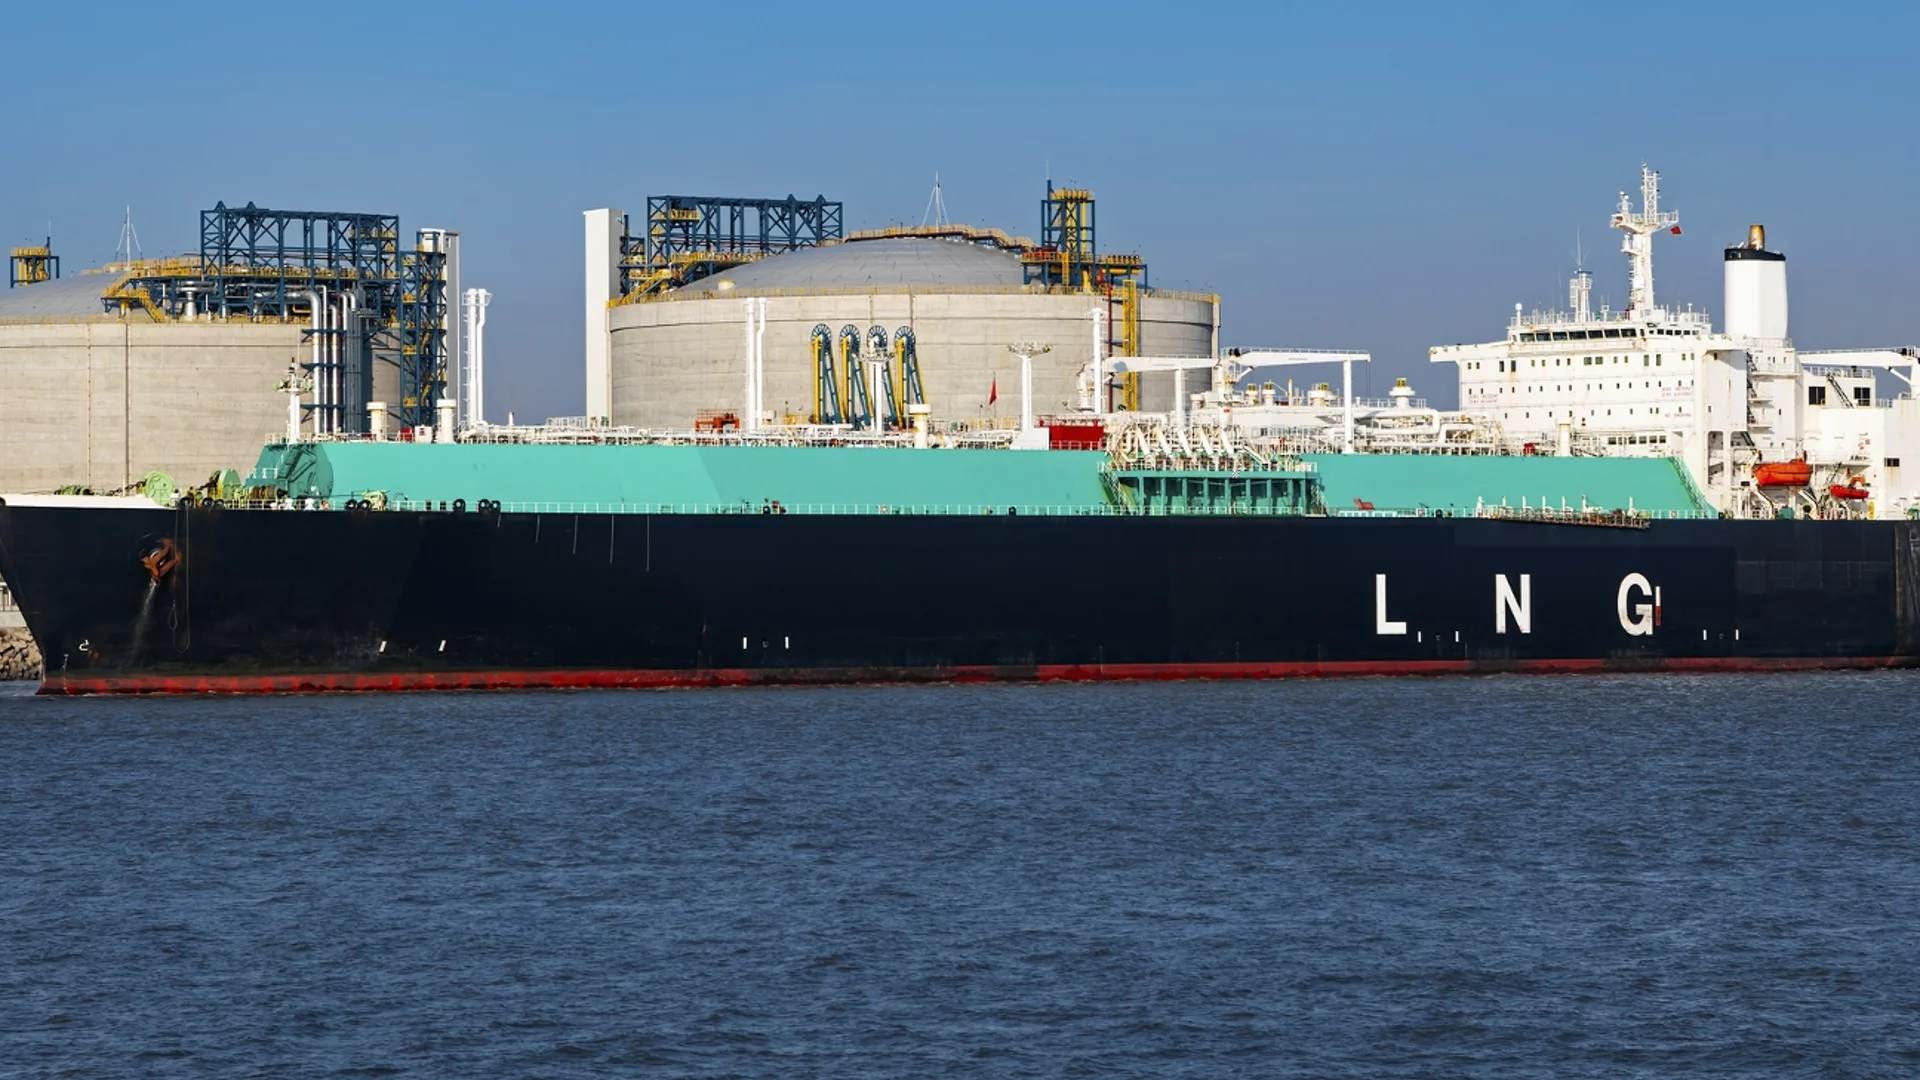
The financial fallout from the conflict highlights a stark divergence in regional resilience. Europe, heavily reliant on spot market purchases, bears the brunt of this instability. Despite a projected decline in regional demand, Europe’s LNG bill is expected to climb by at least $12 billion. Analysts point to a strategic vulnerability: by prioritizing spot liquidity over long-term contracts, European importers have left themselves exposed to the full force of market volatility. The region faces a loss of roughly 20.6 million tonnes of previously scheduled Qatari supply, a shortfall that cannot be easily mitigated.
In contrast, East Asia remains better insulated against these price shocks. Approximately 82% of the region’s long-term contracts are linked to oil prices, which have seen significantly lower growth compared to the spot LNG prices impacting European buyers. While Europe’s average procurement price has surged by 47%, East Asian importers have leveraged a broader, more stable supply portfolio to limit their cost increase to 9.7%.

Comments (0)
No comments yet. Be the first!