
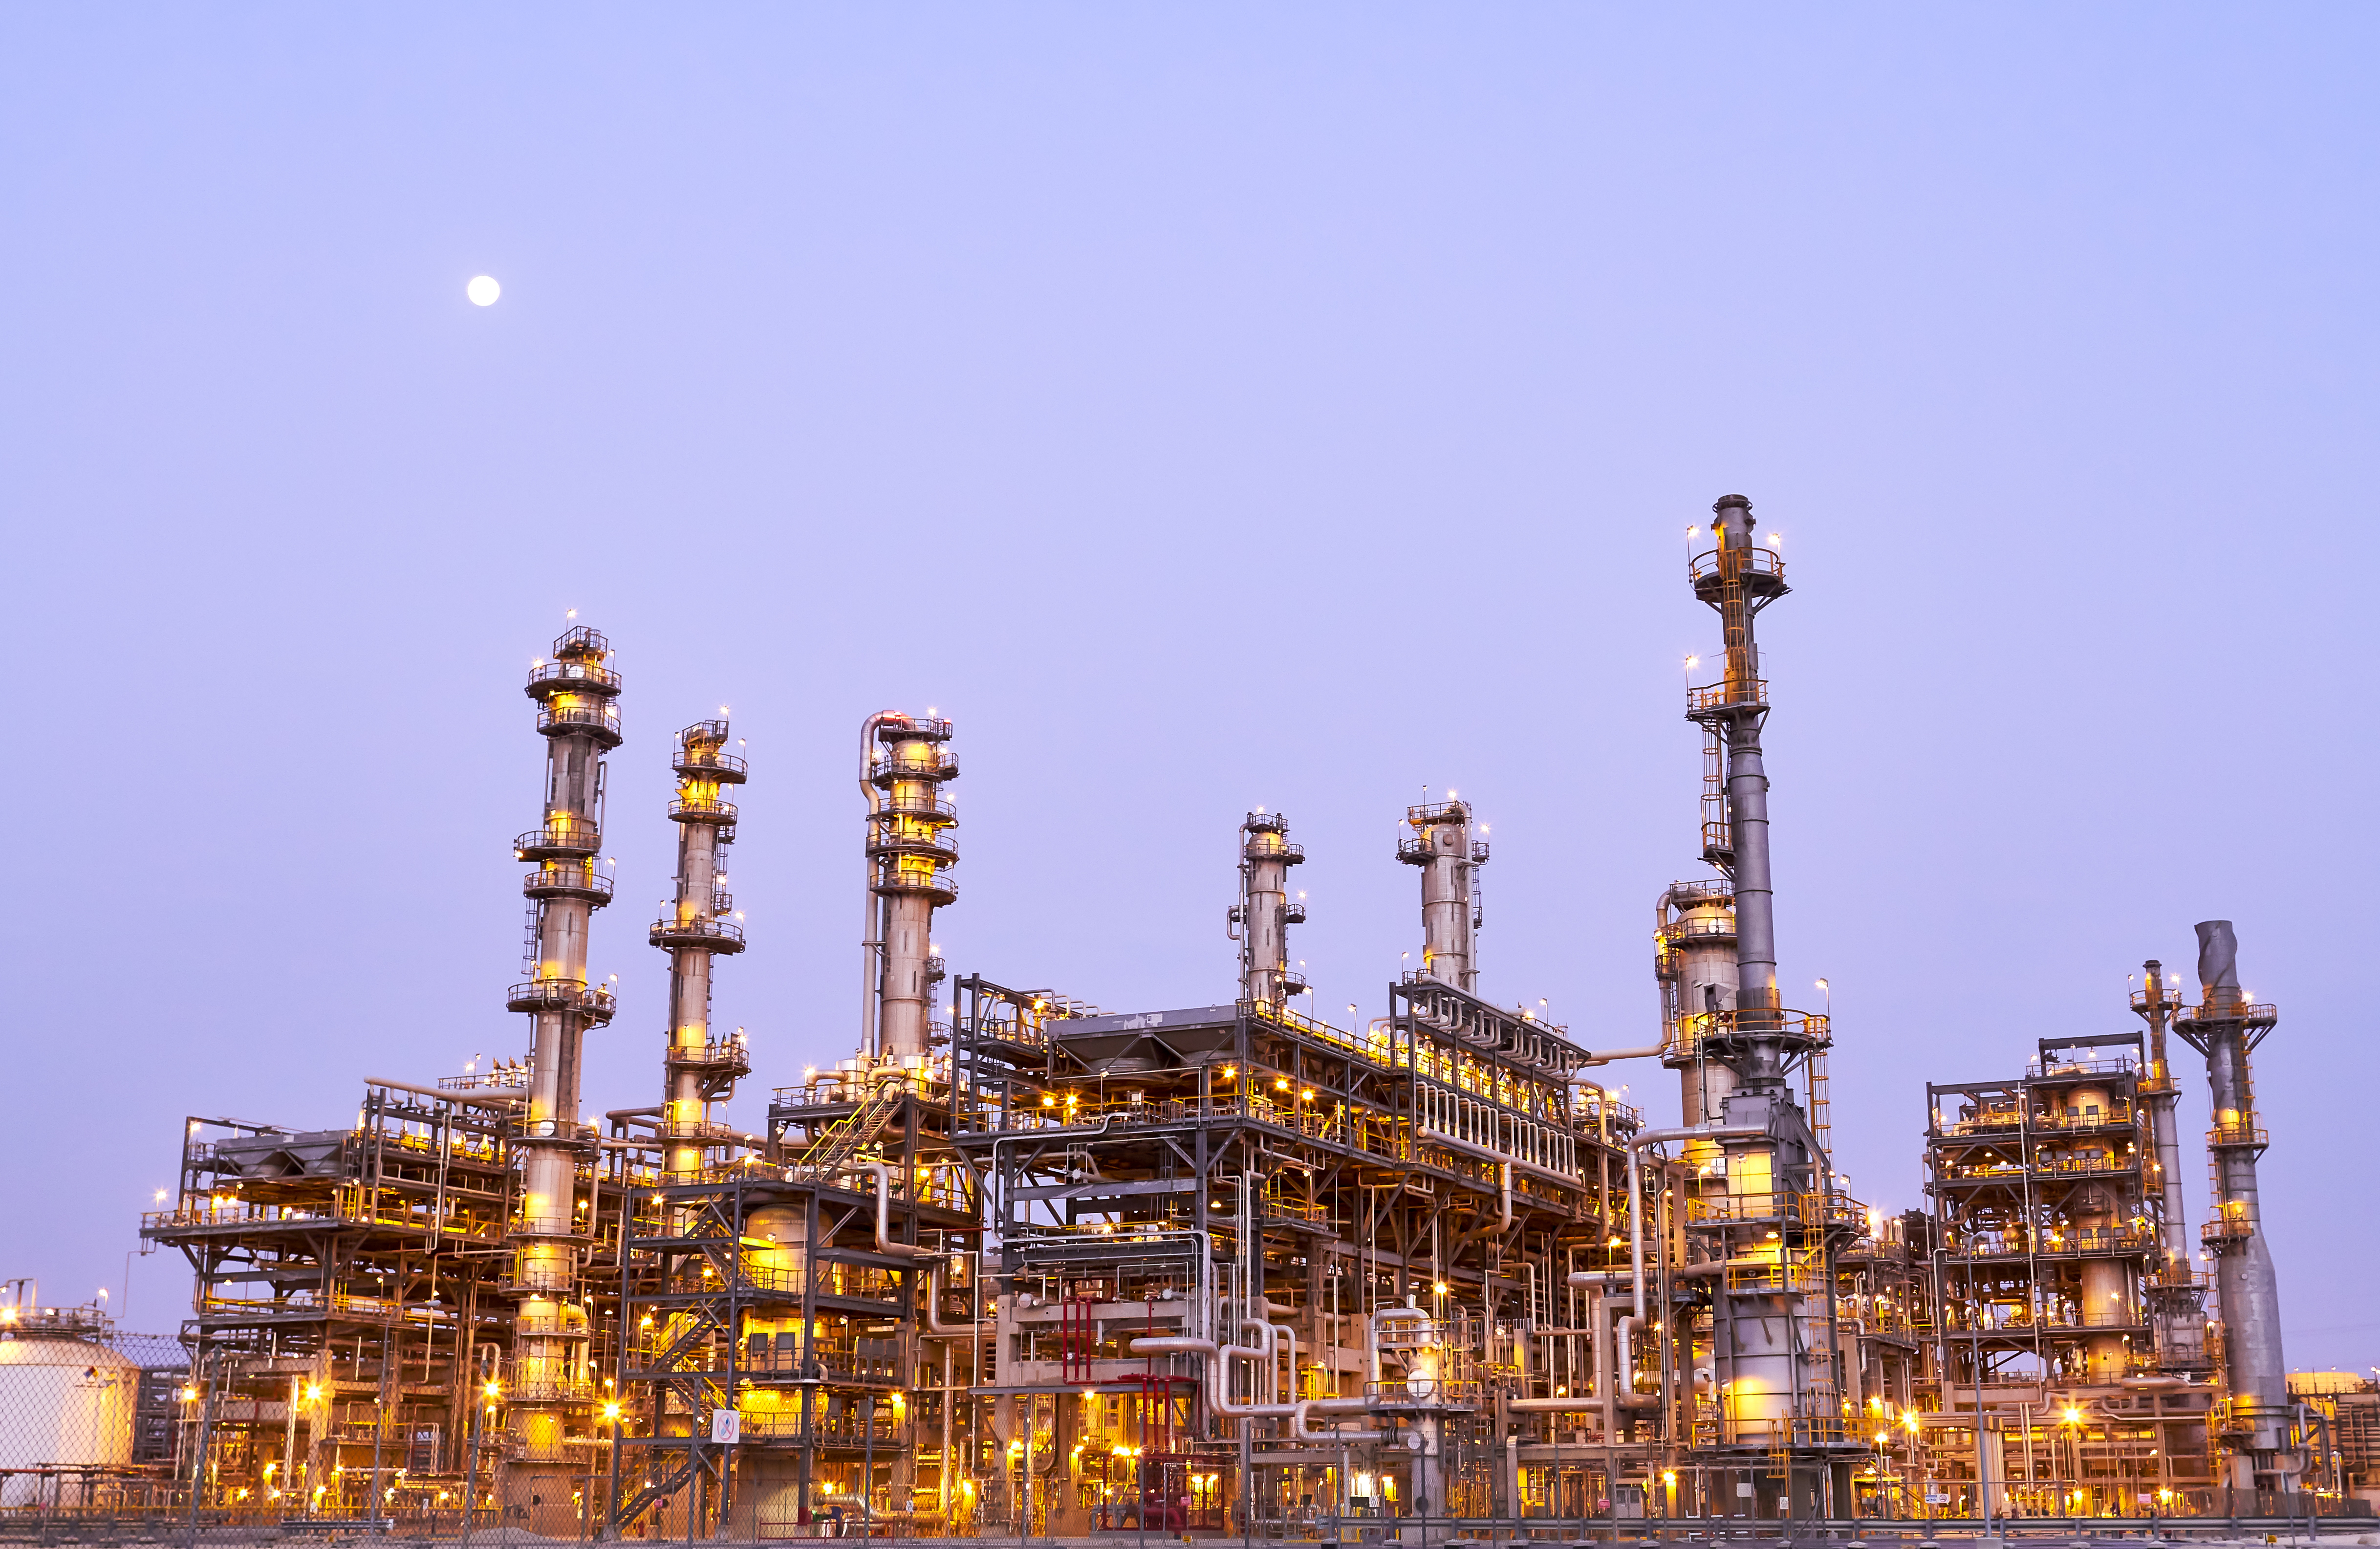
Aramco’s reported $36.25 billion in quarterly net income relies heavily on accounting gains rather than pure production strength. Notably, the company’s exit from the Malaysian PRefChem joint venture generated a $6.91 billion gain, yet much of this remains tied up in receivables to be settled over six years. When stripped of these one-time adjustments, the company’s underlying performance appears more stagnant, with free cash flow failing to cover base dividend payments over the last nine months.
The company is caught between two competing mandates: the corporate need for investment returns and the sovereign demand to fund a Kingdom facing a projected 2026 fiscal deficit of $65 billion. As government spending outpaces revenue growth, the pressure on Aramco to sustain high payouts increases. Simultaneously, the firm is navigating a more hostile landscape for energy exports. With liquids output down and supply reliability slipping to 97.8%, the company is forced to invest in costly alternative export routes and overseas storage to circumvent regional shipping disruptions.
Comments (0)
No comments yet. Be the first!